For the self-employed · Lüdenscheid and the Märkischer Kreis region
Self-employed: retirement, protection and taxes in one plan.
As a self-employed person, nobody but you pays into your pension. There is no continued salary payment, and you have to choose your health insurance yourself. I am Eduard Strekert, financial advisor for Deutsche Vermögensberatung AG in Lüdenscheid, and since 2013 I have helped self-employed people, freelancers and founders in the Märkischer Kreis region put these topics in the right order.
Who this advice is made for.
Self-employed means many things in Lüdenscheid: the trade business with employees, the practice, the freelancer at the computer, the founder in year one. The questions are similar, the answers are not.
Trades and small business
Business, staff, machines. Your own provision often comes last.
Practice and law firm
High income, high tax burden, professional pension fund. What is still missing privately.
Freelancers and IT
Projects instead of a salary. Provision that keeps up with fluctuating income.
Founders
First year, first decisions. What matters now and what can wait.
Four topics self-employed people tend to leave open.
In everyday business there is no time, and none of these topics announces itself. We tackle them in exactly this order.
Topic 1 · Pension
Retirement planning without an employer
Most self-employed people are not compulsorily insured. What you do not build yourself will not exist later. We calculate your pension gap and choose the building blocks that fit your income.
- Basisrente (tax-deductible basic pension): deductible contributions, lifelong pension
- Fund portfolio: flexible when income fluctuates
- Voluntary statutory pension and tangible assets as a supplement
Topic 2 · Income
Ill or unable to work: who pays?
No continued salary payment, no automatic sickness benefit. From the first day of illness the income is gone while the business keeps running. For self-employed people this is the biggest gap and the one closed least often.
- Daily sickness allowance (Krankentagegeld) from the day you choose
- Occupational disability (BU): one in four is affected during their working life (DAV)
- Power of attorney: who decides if you are out of action
Topic 3 · Health
GKV or PKV, your free choice
As a self-employed person you decide yourself. Both routes have their price, and the decision lasts into old age. We compare honestly, with an eye on family, health and the return rule from age 55.
- Statutory health insurance (GKV): family cover, income-based contribution
- Private health insurance (PKV): benefits by tariff, premium by age and health
- Daily sickness allowance belongs in both variants
Topic 4 · Liquidity
Money in the business and privately
How much buffer belongs in the business account, what may leave it, and where does it go then? Tax and provision interlock here. We do the framing together, your tax advisor does the numbers.
- Emergency fund: three to six months of expenses, business and private
- Invest surpluses instead of leaving them idle
- With employees: occupational pension (bAV) and company health insurance (bKV) to retain staff
Three steps to your plan.
Initial consultation
Together we look at where you stand today and what matters to you. In person in Lüdenscheid or by video. Free of charge and without obligation.
Analysis and plan
Income, pension gap, existing contracts, tax situation. From this comes an order: first the foundation, then the returns.
Implementation and support
We put the steps into practice and review the plan once a year. If the business grows or your life changes, we adjust it.
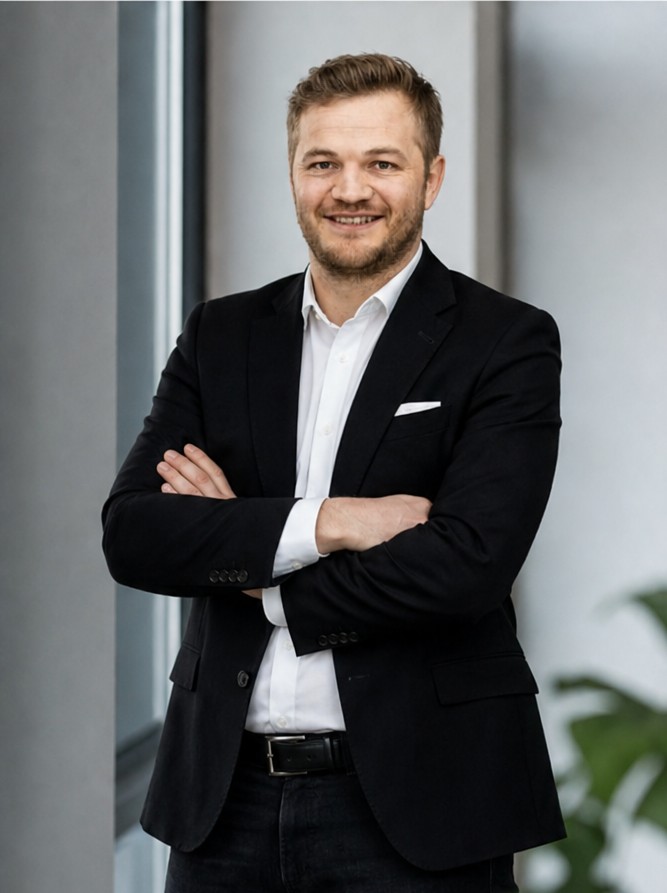
Eduard Strekert, financial advisor in Lüdenscheid.
Since 2013 I have advised private clients, self-employed people and business owners in the Märkischer Kreis region as a financial advisor for Deutsche Vermögensberatung AG (DVAG). My office is at Knapper Straße 24 in Lüdenscheid. I work with fixed product partners, among them Generali, Deutsche Bank and Badenia, and I stay with my clients for years, not just until the signature.
- Insurance intermediary under Sec. 34d GewO (German Trade Regulation), financial investment intermediary under Sec. 34f GewO, mortgage credit intermediary under Sec. 34i GewO
- Advice in German and Russian, website also in English
- In person in the Märkischer Kreis region, in Iserlohn, Schwerte and Dortmund; by video across Germany
Initial information under Sec. 15 VersVermV (German) with all details on status and remuneration.
Read on: knowledge for the self-employed.
The most common questions from my consultations, answered in detail.
Frequently asked questions from self-employed people.
Who advises self-employed people in Lüdenscheid on retirement planning?
Do I have to pay into the statutory pension scheme as a self-employed person?
Which retirement plan makes sense for self-employed people without a statutory pension?
What happens if I fall ill for a longer period as a self-employed person?
Can I deduct pension contributions from tax as a self-employed person?
GKV or PKV: which is better for self-employed people?
What does the advice for self-employed people cost?
Do you also advise outside Lüdenscheid?
Free & without obligation
Let's talk about your situation.
A first conversation, in person in Lüdenscheid or by video. We look at which of the four topics is up first for you. No pressure, at your pace.